Mobile Home Insurance
In short
Mobile home insurance covers a manufactured or mobile home and your belongings after a covered loss such as fire, wind or hail, covers your liability if someone is hurt or their property is damaged, and helps with living costs while the home is being repaired. FCI Agency represents many carriers and compares their policies for you, at no additional cost to you, and your advisor stays your one contact.
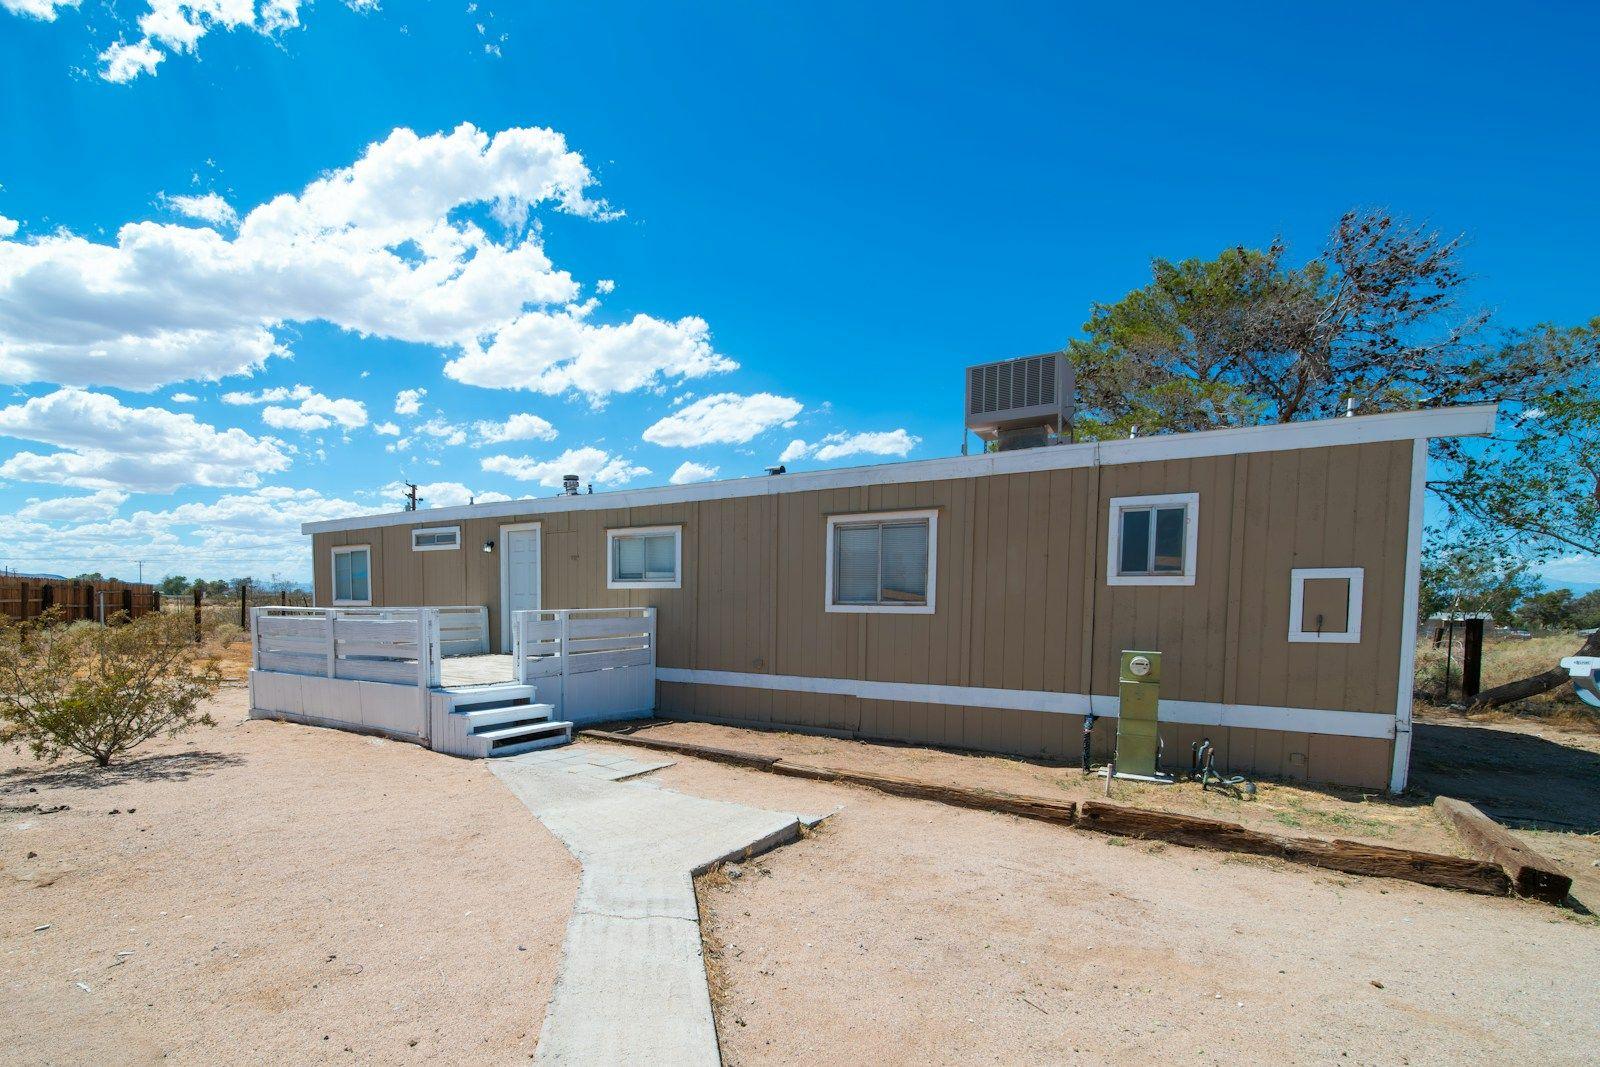
Mobile home insurance with FCI Agency
A manufactured or mobile home is built and set up differently from a site-built house, so it needs a policy written for it. Your FCI advisor compares carriers that insure mobile homes, whether yours sits on your own land or in a community, and stays your one contact for claims and changes.
What mobile home insurance covers
Coverages and their names vary by carrier and policy; your advisor shows you what each quote includes.
- The home
- Repairs or replaces the home after a covered loss, including attached additions such as a porch, steps or a carport. Ask whether your policy pays the cost to replace it or its depreciated value.
- Other structures
- Covers a shed, a detached carport, a deck or a fence on the property.
- Personal property
- Covers your belongings, such as furniture, clothing and electronics, if they are damaged or stolen.
- Loss of use
- Helps pay extra living costs, such as a hotel and meals, while a covered loss leaves your home unlivable.
- Personal liability
- Covers your legal responsibility if someone is injured or their property is damaged and you are at fault, including the cost of defending you.
- Moving the home
- Damage while the home is being moved to a new site is covered only if you add transportation coverage before the move.
What a policy may not cover
Flooding: water that rises from outside. Flood insurance is a separate policy.
What is Flood Insurance?Wear and tear, rust, and damage from neglect or a slow leak over time.
Damage from termites, insects or rodents.
The community’s own property, which the park or community insures itself.
What drives the price
Your advisor compares these across carriers for you.
The home itself
Its age, make and size, and the condition of the roof, plumbing, wiring and heating.
How it is set up
How the home is anchored and tied down, and whether it has skirting and a permanent foundation.
Where it is
Weather risk in your area, the distance to a fire station, and whether the home is on your own land or in a community.
Your coverage and deductible
Replacement cost costs more than depreciated-value coverage, and a higher deductible lowers your premium. Many policies carry a separate deductible for wind or hail.
Mobile home insurance questions
Usually not. Manufactured and mobile homes are built and set up differently from site-built houses, so carriers insure them on policies of their own, priced on the home’s age, make and tie-downs. Your advisor can compare carriers that write them.
No. A park or community insures its own property and liability. Your home, your belongings and your liability need a policy of your own, and many communities and lenders require one.
A policy written for a rental, not the one for a home you live in. See landlord insurance, or ask your advisor.
Your mobile home insurance advisors
Call or email any of them, or send the form below.
Jason Acosta
Personal Lines Account Manager
Carolyn Hilton
Personal Lines Manager
Anna Hobbs
Personal Lines Account Manager
Candice Bishop
Marketing and Account Manager
Specializes as an Account Manager in personal lines.
Amanda Hopper
Insurance Advisor
Get a quote
What happens next
Step 1: Tell us what you need
Share what you have today and what you want covered, online or on a call.
Step 2: We compare the carriers
Your advisor compares plans from the carriers we represent, at no additional cost to you.
Step 3: You choose, and keep one contact
Your advisor walks you through the options and stays your one, easy-to-reach contact after you buy.